A packed appointment book doesn't guarantee a profitable salon. Many owners check the bank balance every Friday. They see a healthy number and assume business is good. But that balance includes rent money, retail float, and next week's payroll. It tells you what's in the account today. It says nothing about whether the salon made money this month.
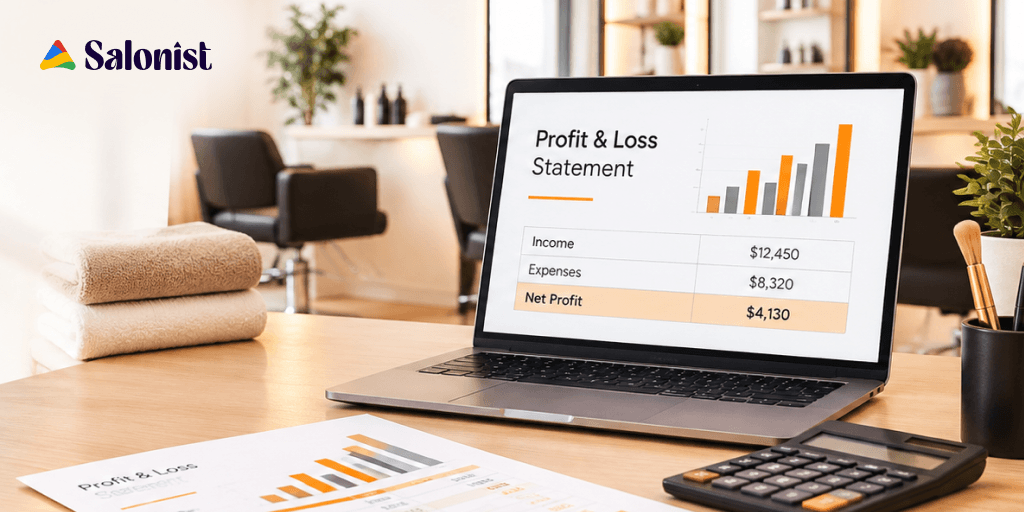
That's what a profit and loss statement is for. It lines up everything you earned against everything you spent over a set period. It shows you, in plain numbers, whether the salon turned a real profit.
Most salon owners have seen a P&L. Fewer have read one line by line. Fewer still know what each section actually means for their business. This guide breaks down the salon profit and loss statement, section by section, in plain language. You'll be able to read your own numbers with confidence, not just forward them to an accountant and hope for good news. A P&L is easier to understand with real figures in front of you, so we've built a free template you can download and start using today.
What Is a P&L for a Salon?
Now that we've established what a P&L statement is, we can move on to explaining each part in detail.
What Do P&L Statements Indicate?
A P&L organizes your salon's finances into four core numbers. Together, they show how the business is really doing.
- Revenue: total money earned from services, retail, and memberships, before any costs come out
- Expenses: everything spent to run the salon, from product costs to rent and payroll
- Gross profit: what's left after you subtract the direct cost of your services
- Net profit or loss: the true bottom line, once every expense is counted
Why Every Salon Owner Should Track Their P&L
Reviewing your P&L regularly changes how you run the business. It's not just a report you file away.
- Understand profitability. Know if the salon is making money, not just moving money.
- Control unnecessary spending. Catch costs that have crept up without adding value.
- Identify revenue opportunities. See which services or products are underperforming.
- Make better staffing and pricing decisions. Set prices and schedules based on real margins.
- Plan growth. Expand or hire based on actual numbers, not a gut feeling.
The Key Sections of a Salon Profit and Loss Statement
Every salon profit and loss statement follows the same basic structure. Here's what each section covers, and why it matters.
1. Salon Revenue
Revenue is more than the total in your booking software. It includes every way the salon brings in money.
- Service revenue from haircuts, color, treatments, and other billable work
- Retail and product sales rung up at checkout
- Memberships and prepaid packages
- Other income, like gift card redemptions and cancellation fees
2. Cost of Goods Sold (COGS)
COGS covers the direct costs tied to a service or a product sale. It's separate from general overhead.
- Hair and beauty products used during services, like color and styling products
- Retail product costs: what you paid your supplier for items you resell
- Other service supplies, like gloves, foils, and disposable tools
Accurate COGS depends on knowing what actually left the shelf, which is where inventory tracking does the heavy lifting.
3. Gross Profit
Formula: Revenue − COGS = Gross Profit
Gross margin reveals how much is left once the actual cost of sales is covered. If the gross margin is small, the focus should be on the cost of production or pricing. Check these before you even glance at rent or payroll.
4. Operating Expenses
Operating expenses are the ongoing costs of running the salon. They show up whether the week was busy or slow.
- Rent
- Payroll and commissions
- Utilities
- Marketing
- Software
- Insurance
- Cleaning and maintenance
- Other overhead
5. Net Profit or Loss
Formula: Gross Profit − Operating Expenses = Net Profit
This is the number that matters most. A positive result means the salon earned more than it spent. A negative one, a net loss, means expenses beat revenue. That can happen even if the calendar looked full all month.
How to Read a Salon P&L Statement Step by Step
Reading a P&L well isn't about scanning it once. It's about following the same steps every time you open it.
Start With Total Revenue
Compare current revenue with past months. Don't look at one number alone. Is it growing, flat, or slipping compared to last month, or the same month last year?
Check Your Cost of Sales
Look at whether product and supply costs are climbing faster than revenue. If COGS eats a growing share of every dollar, check your pricing, your ordering, or how much product you use per service.
Review Your Biggest Operating Expenses
Find the expenses growing faster than revenue. Then split your costs into two groups: essentials like rent and core staff, and spending you could trim without hurting the client experience. Payroll deserves the closest look, since commissions and overtime move the total more than most owners expect. Tracking it through your staff and payroll records keeps that line honest.
Calculate Your Net Profit Margin
Formula: Net Profit ÷ Revenue × 100
This is the ratio of how much profit you make per dollar earned. A salon earning $50,000 monthly with a 10% margin keeps $5,000, while another earning the same amount with a 20% margin keeps $10,000. Same sales. A very different business underneath.
Compare Your Numbers Month Over Month
Look for patterns across several months. Don't judge the business on one good or bad month alone. This also helps you spot a real problem, instead of mistaking it for a normal seasonal dip.
What Are Healthy Numbers for a Salon?
Revenue tells you how much money came in. It doesn't tell you whether the salon is actually healthy.
Revenue vs. Expenses
A salon can earn more every year and still struggle if expenses climb just as fast. Revenue alone is only half the story. Profit is what funds payroll, growth, and your own paycheck.
Understanding Your Salon's Profit Margin
Gross margin shows how efficiently you deliver services, before overhead. Net margin shows what's left once everything is paid. Many salons aim for a gross margin of 50% to 65%. Net margins tend to land in the single digits to low double digits. The right number depends on your rent and staffing setup. Margins matter more than topline revenue, because they show how much of what you earn you actually keep.
Warning Signs to Look For in Your P&L
- Revenue rising while profit falls
- Payroll growing faster than revenue
- Product costs rising, with no price adjustment to match
- Marketing spend with no clear return
- Recurring expenses that no longer add value
Free Salon Profit and Loss Statement Template
A P&L is easier to read with real numbers in front of you. This free template gives you a starting point.
What the Free Template Includes
- Monthly revenue tracking
- Cost of goods sold (COGS)
- Operating expenses
- Gross profit
- Net profit
- Profit margin
How to Use the Salon P&L Template
- Enter revenue for the month
- Add your direct costs (COGS)
- Add your operating expenses
- Let the template calculate profit for you
- Review the trend as you add more months
How Salonist Helps You Keep Track of Your Salon's Finances
A spreadsheet works fine, but it depends on you updating it every month. Salon management platforms such as Salonist connect daily operations to your financial reports. The numbers stay current, without the extra manual work.
Get a Clearer View of Your Salon's Performance
Most owners pull numbers from separate systems by hand. Connect your bookings, sales, and staff schedules to your financial reports instead. You get a live view of performance, not a snapshot pieced together after the month ends.
Track Revenue Across Services, Products, and Staff
Salon reporting that breaks revenue down by service, product line, and staff member shows you what's actually working. It also shows you what might be costing more than it earns.
Use Salon Data to Make Better Business Decisions
- Spot trends before they turn into problems
- Improve how you allocate staff and resources
- Set smarter pricing, staffing, and promotions
The reports aren't the point. The decisions they support are. Better financial visibility means fewer surprises at month's end. It also means more confidence when you adjust prices or plan to hire. If you're working through the operational side of the business too, the Salonist blog covers day-to-day topics that tie directly into these numbers.
7 Mistakes Salon Owners Make When Reading a P&L
Even owners who check their P&L often can misread what it's telling them.
- Looking only at revenue. Strong sales can hide thin or negative margins.
- Confusing cash flow with profit. Money in the bank isn't the same as money earned.
- Ignoring small recurring expenses. Small fees add up fast over a year.
- Forgetting product and service costs. Skip COGS, and gross profit means nothing.
- Not tracking payroll carefully. Commissions and overtime shift totals more than owners expect.
- Comparing the wrong time periods. A slow month next to a peak month skews the picture.
- Failing to act on what the numbers show. A P&L only helps if it changes a decision.
How Often Should You Review Your Salon's Profit and Loss Statement?
The right review schedule depends on the decision you're trying to make.
Monthly P&L Reviews
Monthly reviews catch problems early. You can still act on a cost spike or a revenue dip before it grows.
Quarterly Performance Reviews
Quarterly reviews show trends a single month can't. This will show you how your margins are progressing or declining over time.
Annual Financial Planning
Annual reviews inform the bigger calls. Think pricing changes, a new location, or hiring plans for the year ahead.
Turn Your Salon P&L Into a Business Growth Tool
A P&L isn't just paperwork to file away. Used well, it becomes a tool for running a sharper business.
- Use financial data to set realistic revenue targets
- Identify your most profitable services
- Control unnecessary costs before they become habits
- Improve staff productivity based on real numbers
- Plan investments and expansion with real confidence
The shift that matters most: stop just tracking numbers. Start making decisions from them.
Final Thoughts
You don't need an accounting degree to understand your salon's P&L. You need to know a handful of numbers: revenue, gross profit, net profit, and margin. And you need to know what each one is telling you.
Start by downloading the free template. Review your numbers this month. Do it again the following month and the one after. Salon software solutions like Salonist can assist in automating that data collection. But the habit of reviewing them is what turns a P&L from paperwork into a decision-making tool.
Ready to see where your salon's money is really going? Explore how Salonist brings your financial reporting into one place.
FAQs
What is a salon profit and loss statement?
A profit and loss statement lists everything the salon earned and everything it spent over a set period, then shows the difference. It covers revenue, cost of goods sold, gross profit, operating expenses, and net profit, so you can see whether the business actually made money rather than just moved it through the account.
What is a good profit margin for a salon?
Gross margins commonly sit between 50% and 65%, while net margins usually land in the single digits to low double digits. The right figure for your salon depends heavily on rent and staffing model, so trends in your own numbers over several months tell you more than any industry benchmark.
How do I calculate net profit margin for my salon?
Divide net profit by total revenue, then multiply by 100. A salon with $50,000 in monthly revenue and $5,000 in net profit is running a 10% net margin. The same revenue at a 20% margin returns $10,000, which is why margin matters more than topline sales.
What counts as cost of goods sold in a salon?
The direct costs tied to delivering a service or selling a product: color and styling products used on clients, the wholesale cost of retail items you resell, and consumables such as gloves, foils, and disposable tools. Rent, payroll, and marketing are operating expenses, not COGS.
How often should a salon owner review their P&L?
Monthly for catching cost spikes and revenue dips early, quarterly for spotting margin trends a single month can hide, and annually for bigger decisions such as pricing changes, hiring plans, or opening a second location.
Is profit the same as the money in my salon's bank account?
No. The bank balance includes money you already owe, such as rent, supplier invoices, and upcoming payroll, along with prepaid packages and gift cards that represent services you still have to deliver. Profit is what remains after every cost for the period is counted.